The Universal Credit under-25 penalty has become a growing concern for younger benefit claimants across the UK, particularly parents who receive less financial support than older adults despite facing similar living costs.
Under current Department for Work and Pensions (DWP) rules, most claimants aged under 25 receive a lower standard allowance than those aged 25 and over.
The difference can exceed £1,000 annually for single claimants and £1,600 for some couples.
The Government’s proposed Universal Credit rates for 2027/28 confirm that the age-based payment gap is expected to continue, although the standard allowances are set to increase.
This article explains the latest payment figures, how the policy affects young parents, what happens when claimants turn 25 and whether any reforms are planned.
How Does the Lower Universal Credit Allowance Work for Younger Claimants?
Universal Credit provides financial support to eligible people who are unemployed, working on low incomes or unable to work because of certain circumstances.
Every eligible household receives a standard allowance, which forms the starting point for calculating its Universal Credit entitlement.
However, the amount depends partly on age and relationship status.
People aged between 18 and 24 generally receive a lower standard allowance than those aged 25 and over. Certain 16- and 17-year-olds can also qualify for Universal Credit.
The term under 25 penalty is commonly used by campaigners to describe this financial difference. It is not an official DWP penalty or a benefit sanction.
The distinction matters because younger claimants are not receiving reduced payments for breaking benefit rules. They are receiving the rate established for their age category.
Why Do Under-25s Receive Less Universal Credit?
The lower allowance for younger adults reflects an age-based approach that existed in the UK benefits system before Universal Credit was introduced.
Lower rates for younger Jobseeker’s Allowance claimants were introduced in 1996.
Historically, governments have justified age-related benefit differences by arguing that younger adults are more likely to live with relatives, have lower earnings expectations and face fewer independent household expenses.
In a 2019 parliamentary response, the Government referred to younger claimants’ likelihood of living in another person’s household and having lower living costs.
However, welfare organisations have challenged whether these assumptions accurately reflect the circumstances of young adults who rent privately, live independently or have children.
A 24-year-old single parent may face similar expenditure on food, housing and childcare as a 25-year-old parent.
Campaigners therefore argue that determining the basic allowance mainly by age can create inequalities between households with comparable financial responsibilities.
How Much Less Universal Credit Do Under-25s Receive in 2026/27?
The Universal Credit standard allowance depends on whether someone claims individually or as part of a couple.
According to the DWP, the monthly standard allowances for 2026/27 are:
| Claimant Circumstances | Monthly Allowance |
|---|---|
| Single And Under 25 | £338.58 |
| Single And 25 Or Over | £424.90 |
| Couple Both Under 25 | £528.34 |
| Couple With One Or Both Aged 25 Or Over | £666.97 |
Source: GOV.UK Universal Credit Payment Rates.
Financial Difference for Single Claimants
A single person under 25 receives £86.32 less each month than a single claimant aged 25 or over.
Over 12 months, that represents a difference of £1,035.84 in the standard allowance.
For someone paying rent, travelling to work or managing essential household bills, this difference can be financially significant.
Financial Difference for Couples
Couples where both partners are under 25 receive £138.63 less monthly than couples where at least one partner is 25 or older.
That amounts to £1,663.56 across 12 months.
These figures compare the standard allowance only.
Actual Universal Credit payments may include additional elements or deductions depending on earnings, housing costs, children and other circumstances.
Will the Universal Credit Under 25 Penalty Change in 2027?
The DWP published its proposed benefit and pension rates for 2027/28 on 11 November 2026.
The figures indicate that Universal Credit standard allowances will increase, but the existing age categories will remain.
Proposed Universal Credit Rates for 2027/28
| Claimant Circumstances | 2026/27 Rates | Proposed 2027/28 Rates |
|---|---|---|
| Single Under 25 | £338.58 | £353.87 |
| Single 25 Or Over | £424.90 | £443.21 |
| Couple Both Under 25 | £528.34 | £551.11 |
| Couple With One Or Both Aged 25 Or Over | £666.97 | £695.71 |
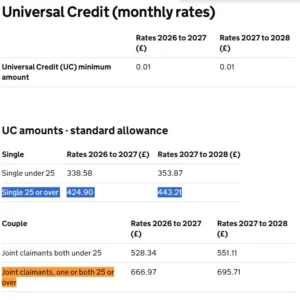
Official DWP figures comparing Universal Credit standard allowances for 2026/27 and the proposed rates for 2027/28.
Under these proposals, a single claimant under 25 would receive £353.87 monthly, an increase of £15.29.
A single claimant aged 25 or over would receive £443.21, an increase of £18.31.
Although both groups would receive higher allowances, the financial difference between them would widen slightly.
Importantly, the 2027/28 figures remain proposed rates as of 21 November 2026.
They should not be presented as final confirmed payment amounts until the relevant legislation and official implementation arrangements are completed.
How Much Could Under-25 Claimants Receive Less Annually in 2027?
The proposed rates show that the age-related financial difference could become larger in 2027/28.
| Claimant Comparison | Monthly Difference | Annual Difference |
|---|---|---|
| Single Under 25 Versus Single 25 Or Over | £89.34 | £1,072.08 |
| Both Partners Under 25 Versus At Least One Partner 25 Or Over | £144.60 | £1,735.20 |
These figures demonstrate the potential annual difference between the standard allowances for different age categories.
For example, two single adults living independently could receive different basic Universal Credit entitlements solely because one is 24 and the other is 25.
However, the figures should not be interpreted as the exact amount every younger claimant will lose.
Individual payments can change because of employment income, benefit deductions, housing support and additional entitlements.
The annual figures also assume that the claimant’s relevant circumstances remain unchanged for 12 months.
Why Are Young Parents Most Affected by the Universal Credit Under 25 Penalty?
Young parents have become a major focus of the debate because raising a child involves substantial expenses regardless of a parent’s age.
Households with children must consider housing, food, clothing, childcare and other everyday necessities.
Campaigners argue that these costs do not automatically become lower because a parent is 22 or 24 rather than 25.
Consider two single parents who have similar incomes, live in comparable rented accommodation and are responsible for children of the same age.
If one parent is 24 and the other is 25, the younger parent would normally receive a lower Universal Credit standard allowance.
Both may qualify for additional child-related support, but this does not remove the difference between their standard allowances.
The issue is particularly important for families already struggling to meet essential expenses.
A reduction in basic financial support can leave younger parents with less money available after paying for accommodation, utilities and food.
Campaigners have therefore described the policy as a young parent penalty, arguing that the benefits system should better recognise parental responsibilities rather than relying primarily on age.
What Does Resolution Foundation Research Reveal About the Young Parent Penalty?
The Resolution Foundation highlighted the impact of age-related benefit differences in research published in October 2019.
Its findings examined how younger single parents were affected when moving from the previous benefits system to Universal Credit.
The research estimated that:
- 67% of younger single parents experienced an income reduction when moving to Universal Credit.
- 32% Of Younger Single Parents: Experienced an income increase.
- 56% Of Single Parents Aged 25 or over experienced an income reduction.
- 41% Of Older Single Parents: Experienced an income increase.
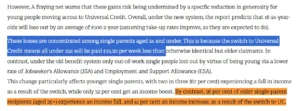
Resolution Foundation research showing the different financial outcomes estimated for younger and older single parents moving to Universal Credit.
The findings suggested that younger single parents were more likely to experience a reduction in income during the transition.
The organisation called for stronger financial protection for younger families, including aligning the basic allowances for young single parents with those available to older parents.
However, these statistics relate specifically to research published in 2019.
They describe estimated changes during the transition from legacy benefits to Universal Credit.
They should not be treated as current 2026 claimant statistics or attributed entirely to the age-based allowance difference.
Nevertheless, the findings provide important historical evidence explaining why welfare organisations continue to question the treatment of younger parents.
What Happens to Your Universal Credit When You Turn 25?
Turning 25 can increase a claimant’s standard Universal Credit allowance.
For a single claimant, the applicable standard allowance changes from the under-25 category to the rate for people aged 25 or over.
Under 2026/27 rates, that difference is £86.32 monthly.
A claimant does not normally need to make a completely new Universal Credit application simply because they reach their 25th birthday.
However, Universal Credit is assessed through monthly assessment periods, and the payment calculation depends on the claimant’s circumstances.
Claimants should check their Universal Credit statement to ensure the appropriate allowance has been applied.
What If One Partner Turns 25?
For couples, the higher standard allowance applies where either partner is aged 25 or over.
This means a couple where both partners were previously under 25 may move into the higher age category when one partner reaches 25.
Their payment may still be affected by earnings, deductions and other household circumstances.
Anyone who believes the incorrect rate has been applied should contact the DWP through their Universal Credit journal.
Can 16 and 17-Year-Old Parents Claim Universal Credit?
Although Universal Credit is generally available to people aged 18 or over, some younger claimants can qualify.
Official DWP guidance allows certain 16- and 17-year-olds to claim when specific conditions are met.
These include circumstances where someone:
- Is Responsible for a Child: Young parents may qualify before reaching 18.
- Is Pregnant: Eligibility may apply when the baby is expected within the next 11 weeks.
- Has Recently Given Birth: Someone who had a baby within the previous 15 weeks may qualify.
- Has No Parental Support: Certain young people unable to receive support from their parents may be eligible.
- Has a Qualifying Health Condition: Medical evidence may support eligibility in specified circumstances.
- Has Caring Responsibilities: Eligibility may apply when caring for someone receiving a qualifying health or disability benefit.
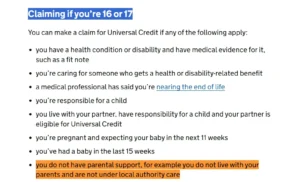
Official DWP eligibility guidance confirming the circumstances in which 16- and 17-year-olds can claim Universal Credit.
Eligibility depends on the claimant’s circumstances, and meeting an age exception does not automatically guarantee a payment.
Young people in education should also check the relevant rules, as full-time students usually face additional eligibility restrictions.
Does the Under-25 Penalty Affect Housing and Childcare Support?
The lower standard allowance does not automatically prevent claimants from receiving housing or childcare assistance.
Universal Credit consists of different elements that may be added when a household qualifies.
Housing Support for Younger Claimants
Eligible renters may receive a housing costs element to help with their rent.
However, different rules apply to certain private renters aged under 35.
Single private renters under 35 who do not live with a partner or children are often limited to the shared accommodation rate of Local Housing Allowance.
There are exceptions, and the rules differ for people responsible for children or living in certain other circumstances.
Therefore, the under-25 standard allowance and the under-35 housing rules are separate issues.
Childcare Support for Young Parents
Working parents receiving Universal Credit may qualify for reimbursement of up to 85% of eligible registered childcare costs.
Under the current 2026/27 rules, the maximum childcare support is:
| Childcare Circumstances | Maximum Monthly Support |
|---|---|
| One Child | £1,071.09 |
| Two Or More Children | £1,836.16 |
These limits apply subject to the claimant meeting the relevant eligibility conditions.
Parents generally need to pay childcare costs and report them through their Universal Credit account, although help with upfront costs may be available when starting or increasing work.
The Government has also outlined a different structure for the maximum childcare support available for multiple children in 2027/28.
Younger parents should therefore check the latest official rules when planning future childcare expenses.
What Additional Financial Support Can Young Parents Claim?
Parents under 25 may qualify for other support depending on their income, household circumstances and where they live.
Potential assistance includes:
- Universal Credit Child Element: Additional payments for eligible children within the household.
- Child Benefit: Financial support for people responsible for eligible children.
- Council Tax Reduction: Help with council tax bills for qualifying low-income households.
- Healthy Start Support: Assistance with eligible food and nutritional costs for qualifying families in England, Wales and Northern Ireland.
- Scottish Child Payment: Additional support for eligible low-income families living in Scotland.
- Childcare Assistance: Support with qualifying childcare expenses when working or entering employment.
- Budgeting Advances: Repayable assistance for certain essential expenses, subject to eligibility.
The removal of the Universal Credit two-child limit from 6 April 2026 is another important change for larger families.
That reform affected child-related Universal Credit support, but it did not abolish the separate under-25 standard allowance.
Claimants should use an independent benefits calculator or seek advice from a qualified welfare adviser to identify support for which they may be eligible.
Could the Government Scrap the Universal Credit Under 25 Penalty?
Campaigners have repeatedly called for changes to the age-based payment structure.
Their central argument is that younger adults living independently or raising children may face financial responsibilities similar to those of older claimants.
Proposals have included equalising standard allowances for different age groups and providing greater protection for young parents.
The Resolution Foundation specifically recommended improving the basic support available to younger single parents.
However, campaign proposals must be distinguished from confirmed government decisions.
As of 21 November 2026, there is no confirmed government decision to abolish the lower Universal Credit standard allowance for under-25s in 2027.
The DWP’s proposed 2027/28 rates continue to distinguish between younger and older claimants.
While welfare policy remains subject to political discussion and potential future reform, there is no basis for telling claimants that the existing age-related payment gap is about to disappear.
Any future changes would require official confirmation, and claimants should rely on published DWP guidance rather than speculation.
What Should Under-25 Universal Credit Claimants Do Next?
Anyone receiving the lower standard allowance should check that their entitlement accurately reflects their circumstances.
Practical steps include:
- Check Your Universal Credit Statement: Review the standard allowance and any additional amounts included in your monthly award.
- Review Your Entitlement When Turning 25: Make sure the higher age-related allowance is applied when appropriate.
- Report Changes in Circumstances: Inform the DWP promptly about relevant changes involving children, housing, employment or relationships.
- Check Childcare and Housing Support: Explore the additional elements available for eligible households.
- Use an Independent Benefits Calculator: Estimate potential entitlement based on current income and personal circumstances.
- Seek Welfare Advice: Contact Citizens Advice or another qualified adviser if you believe your payment is incorrect.
- Follow Official 2027 Updates: Check the final DWP benefit rates before relying on proposed payment figures.
Claimants should also remember that the under-25 allowance is not the same as a benefit sanction.
A sanction is a separate reduction that may apply when someone does not meet certain Universal Credit requirements without an accepted reason.
The age-based allowance applies because of the claimant’s circumstances, not because they have failed to comply with DWP rules.
Conclusion
The Universal Credit under 25 penalty remains an important financial issue for younger adults and families across the UK.
Under the 2026/27 rates, single claimants under 25 receive £86.32 less monthly than those aged 25 or over, while younger couples can face a difference of £138.63.
The proposed 2027/28 figures suggest the gap will remain and may increase slightly, despite higher standard allowances for both age groups.
Research from the Resolution Foundation has highlighted the financial difficulties faced by younger parents, particularly during the transition from older benefits to Universal Credit.
Although campaigners continue to advocate reform, no confirmed decision has removed the age-based standard allowance.
Younger claimants should therefore understand the current payment rules, check their eligibility for additional support and follow official announcements about future changes.
FAQs
Is the Universal Credit Under 25 Penalty Being Removed in 2027?
No abolition has been confirmed. The proposed 2027/28 Universal Credit rates retain separate standard allowances for claimants under 25 and those aged 25 or over.
How Much Universal Credit Will a Single Person Under 25 Receive in 2027?
The proposed 2027/28 standard allowance is £353.87 monthly for a single claimant under 25, before additional elements or deductions.
Does Universal Credit Automatically Increase When You Turn 25?
Your standard allowance should move to the higher age category when you qualify. Check your payment statement and contact the DWP if the increase is missing.
Do Single Parents Under 25 Receive Less Universal Credit?
They generally receive a lower standard allowance than single parents aged 25 or over, although they may qualify for the same types of additional child-related support.
Can You Claim Universal Credit at 17 if You Have a Child?
Yes, a 17-year-old responsible for a child may qualify for Universal Credit, provided the other relevant eligibility requirements are met.
Can Under-25s Receive Universal Credit Housing and Childcare Support?
Yes. Eligible younger claimants can receive housing and childcare elements, subject to the relevant rules and circumstances.
Is the Under-25 Universal Credit Rate the Same as a DWP Sanction?
No. The lower rate is part of the standard age-based allowance structure, whereas a sanction is a separate reduction for failing to meet certain benefit requirements without an accepted reason.